

Home About us
Independent since 2012
Sittingbourne · Aldershot
Clear, honest advice for your financial future
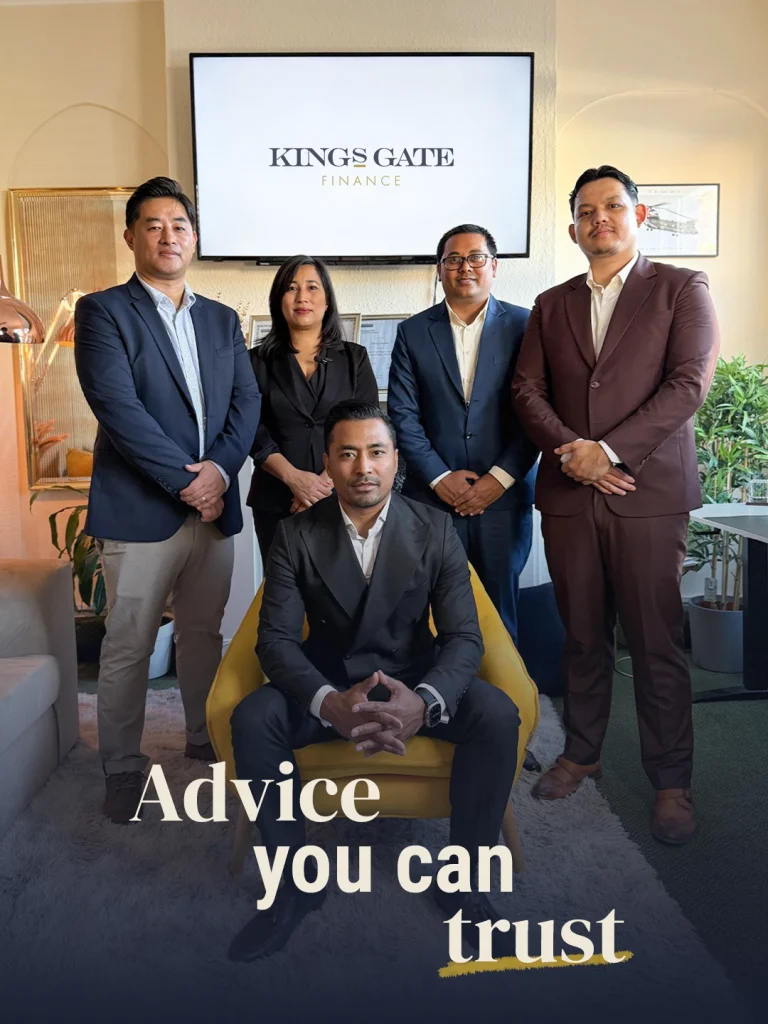
Since 2012, Kings Gate Finance has helped homeowners, families and landlords across Berkshire, Hampshire and Kent with mortgage and protection advice. We’re independent, we search the whole market, and we put you first.
What makes us different
Market-wide expertise
Deep market insight for solutions built around you, with access to whole-of-market lenders.
Personalised consultations
Bespoke advice at your doorstep: in person, by phone or in an online meeting.
Client-first approach
Your goals are our focus, from the first call until you have the keys.
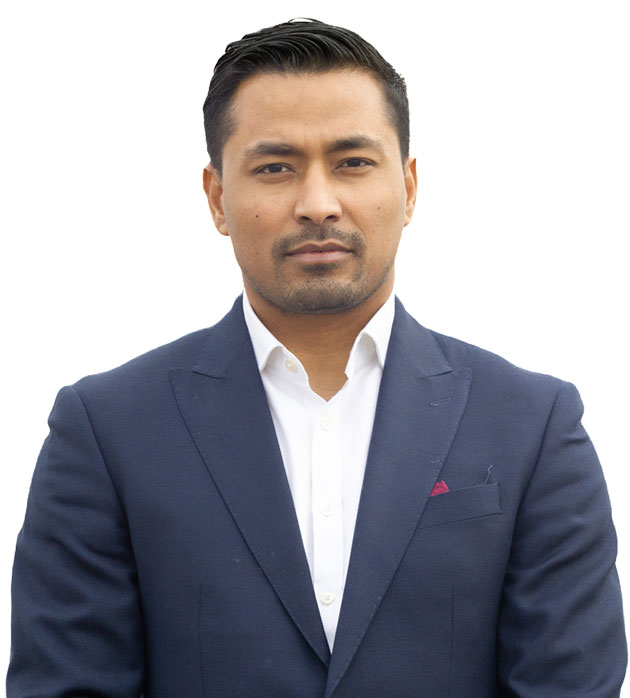
Prajesh Shrestha
Managing Director, since 2012
Our story
Bridging the gap between lenders and people
Kings Gate Finance was founded in 2012 by Managing Director Prajesh Shrestha, who has worked in financial services ever since. The idea was simple: explain complex things clearly, offer face-to-face advice that’s tailored to each client, and always put the client first.
Today our CeMAP-qualified advisers work from offices in Sittingbourne and Aldershot, helping first-time buyers, movers, landlords, the self-employed and Armed Forces families. As an FCA-regulated firm, we take compliance, adviser competence and protecting our clients seriously.
Some of the lenders and insurers on our panel
Barclays Santander Nationwide Accord Coventry Principality Darlington Scottish Widows Aviva Legal & General LV= Royal London Zurich Aegon
Your questions, answered
What is a buy-to-let (BTL) mortgage?
A loan for buying a property to rent out. It’s usually assessed on the rental income the property can generate rather than your personal income, typically 125–145% of the mortgage payment.
What is an Income Booster mortgage?
A family member’s income, such as a parent’s, is added as a “silent” borrower to increase affordability, up to 6× salary with some lenders, without them owning the property. It suits sole buyers with an income gap and is also called a Joint Borrower Sole Proprietor mortgage.
How does remortgaging work, and when should I consider it?
You switch your mortgage to a new deal for a better rate, to release equity or to change your term. Start 3–6 months before your fixed period ends. We compare the whole market and can move you to a better deal if one appears before your fix finishes.
What is a commercial mortgage, and who qualifies?
A mortgage to buy business property such as shops or offices. It’s suited to business owners and investors.
What does life insurance cover?
It pays a lump sum to your beneficiaries if you die, to help cover the mortgage, debts or family income.
How is critical illness cover different from life insurance?
Critical illness cover pays out while you’re alive, when you’re diagnosed with a serious condition such as cancer or a heart attack. It can help you repay the mortgage early or support your lifestyle. Many people combine both, and we’ll advise based on your family’s needs and health history.
What is income protection insurance?
It replaces up to 70% of your earnings if illness or injury stops you working, usually tax-free and up to age 65. It’s especially valuable for the self-employed and property investors.
What is capital raising, and is it right for me?
Capital raising lets homeowners unlock money from their property without moving, for home improvements, investment or buying another property. Whether it’s right depends on your situation, so talk to us first.
What are the risks of releasing equity from my property?
Releasing equity can reduce the inheritance you leave, increase your debt as interest compounds, and affect means-tested benefits. Negative equity is possible if house prices fall. Our free consultation explains the risks and safeguards, such as no-negative-equity guarantees.
What is a will, and do I need one?
A will sets out how your assets, like property and savings, are shared after you die. It helps avoid disputes and inheritance tax pitfalls. We believe everyone should have one.
What is conveyancing?
Conveyancing is the legal transfer of property ownership when you buy or sell. We refer clients to trusted solicitors who offer fast, fixed-fee conveyancing.
Who is Kings Gate Finance, and how can I get in touch?
We’re an independent, whole-of-market broker founded in 2012 by Managing Director Prajesh Shrestha, with offices in Sittingbourne and Aldershot. Email info@kingsgatefinance.com or call 0333 090 1616 for a free initial consultation.
No offer, no fee
We make mortgages simple for you
Expert advice and support at every step, tailored to your circumstances. Your first consultation is free.
